
Trade BTC & ETH Perpetuals
Open isolated long or short synthetic positions against the protocol LP. Margin and leverage determine notional exposure, while the interface surfaces the bust price before a position is submitted.
Trade perpetuals →1000x leverage
0 market impact
100% user owned
fully onchain on hyperliquid
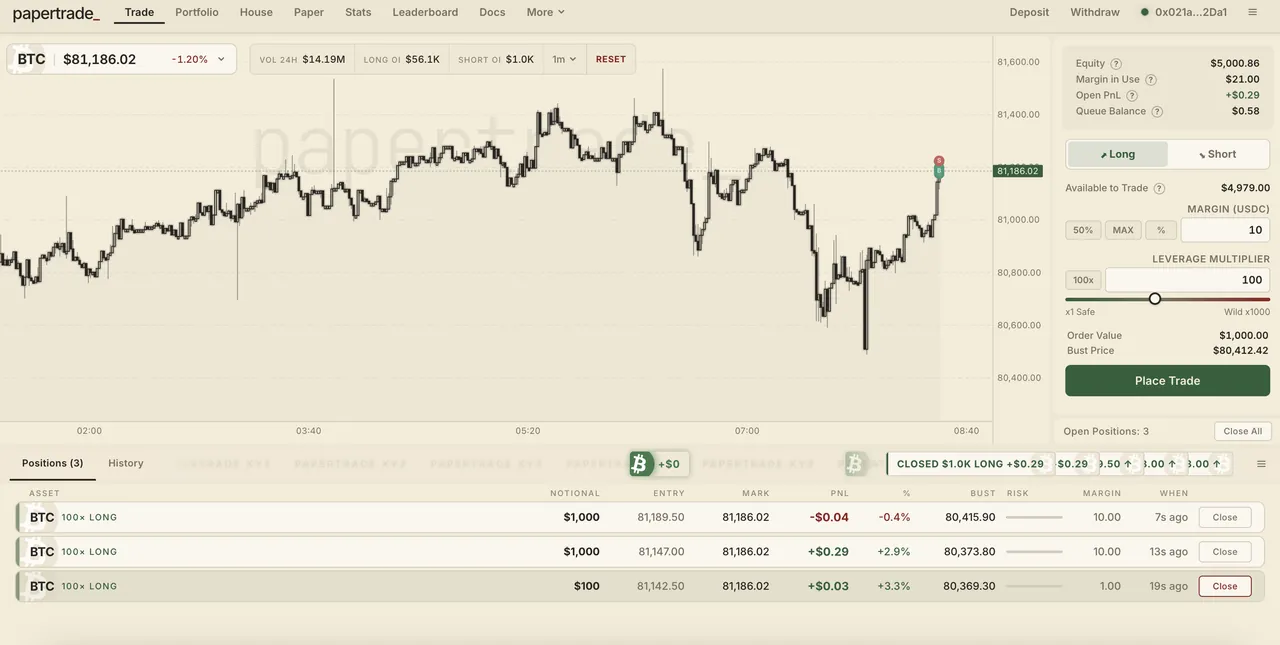
Papertrade is a fully onchain synthetic perpetuals exchange in the Hyperliquid ecosystem. Trade BTC and ETH with leverage up to 1000x using Hyperliquid BBO-mid pricing, explore protocol LP mechanics, follow PAPER emissions and access PAPER staking with available USDC distributions.
Open isolated long or short synthetic positions against the protocol LP. Margin and leverage determine notional exposure, while the interface surfaces the bust price before a position is submitted.
Trade perpetuals →Papertrade reads Hyperliquid best bid and ask state through HyperEVM precompiles. Their midpoint is used as the documented execution reference instead of a separate Papertrade orderbook.
Read BBO pricing →PAPER supply is tied to eligible realized losses and liquidations under the protocol mint curve. The documented fair-launch model begins from zero supply rather than a conventional pre-mint allocation.
Explore PAPER →Staked PAPER can participate in available protocol USDC revenue distributions. Distribution amounts are variable and depend on protocol activity rather than a guaranteed fixed yield.
Open staking →A Papertrade position is a synthetic swap between a trader and the protocol LP. The Exchange contract runs on HyperEVM, reads HyperCore market state through precompiles and settles PnL through protocol accounting rather than matching a trader with another trader.
The House view exposes protocol-side liquidity and market exposure. If immediately available LP liquidity cannot settle eligible winning profit, the documented model can place unpaid profit into a FIFO payout queue. Open interest and queue data provide context but do not guarantee future solvency or execution.
Leverage up to 1000x creates an extremely small distance to liquidation. BBO-based execution does not remove market, liquidity, protocol or liquidation risk. Review margin, bust price, open-interest controls and the risk documentation before opening a high-leverage position.
Papertrade focuses its documented market experience on BTC and ETH synthetic perpetuals. A trader selects a market, chooses a long or short direction, commits isolated margin and sets leverage, while the protocol uses Hyperliquid best-bid and best-ask state as the execution reference. Because the position is a synthetic swap against the protocol LP rather than a Hyperliquid perpetual contract changing hands, Papertrade can expose its own margin, open-interest and settlement rules while still using Hyperliquid market state for price discovery. This makes Papertrade BTC perps, Papertrade ETH perps, high-leverage long and short trading, BBO pricing and liquidation mechanics distinct search and product concepts inside the same protocol.
PAPER connects the trading side of Papertrade with the staking side of the protocol. The published model describes PAPER as being minted from eligible realized trading losses and liquidations rather than from a conventional pre-mint or fixed emission schedule. When PAPER is staked, holders can participate pro rata in documented USDC revenue distributions sourced from eligible protocol economics. That means the important Papertrade search intents are connected but not interchangeable: perpetual trading is the leveraged market product, PAPER emissions describe how token supply grows, and PAPER staking describes participation in available USDC distributions. Rewards are variable and depend on protocol activity and actual distributions rather than a guaranteed fixed APY.
Papertrade does not operate a separate trader-to-trader orderbook. Opens and closes reference Hyperliquid BBO mid and settle synthetically against the protocol LP. The documentation describes no conventional funding cost, spread or trade-size slippage in the normal execution model, although profitable closes can still be reduced by asymmetric impact and protocol settlement mechanics. Directional open-interest limits, LP liquidity, the payout queue and hard liquidation thresholds remain material risk controls, especially when using very high leverage.
Papertrade is a fully onchain synthetic perpetuals exchange in the Hyperliquid ecosystem. Trading logic runs on HyperEVM and uses Hyperliquid BBO-mid pricing as the execution reference.
The published documentation describes BTC and ETH as the initial synthetic perpetual markets, with leverage available up to 1000x subject to market and open-interest limits.
Papertrade uses synthetic swaps against the protocol LP rather than its own orderbook. The documented model does not use conventional funding costs, spread or trade-size slippage.
PAPER is the protocol token minted from eligible realized losses and liquidations under the documented emission model.
Staked PAPER can participate in available USDC revenue distributions according to the protocol staking and distribution mechanics.
Papertrade reads Hyperliquid best bid and ask state through HyperEVM precompiles and uses the BBO midpoint as the execution reference.
The protocol documentation describes a FIFO payout queue for eligible unpaid winning profit when immediately available LP liquidity is insufficient.
Yes. Very high leverage leaves a small distance to liquidation, and crossing the bust price can result in the loss of the isolated margin.